
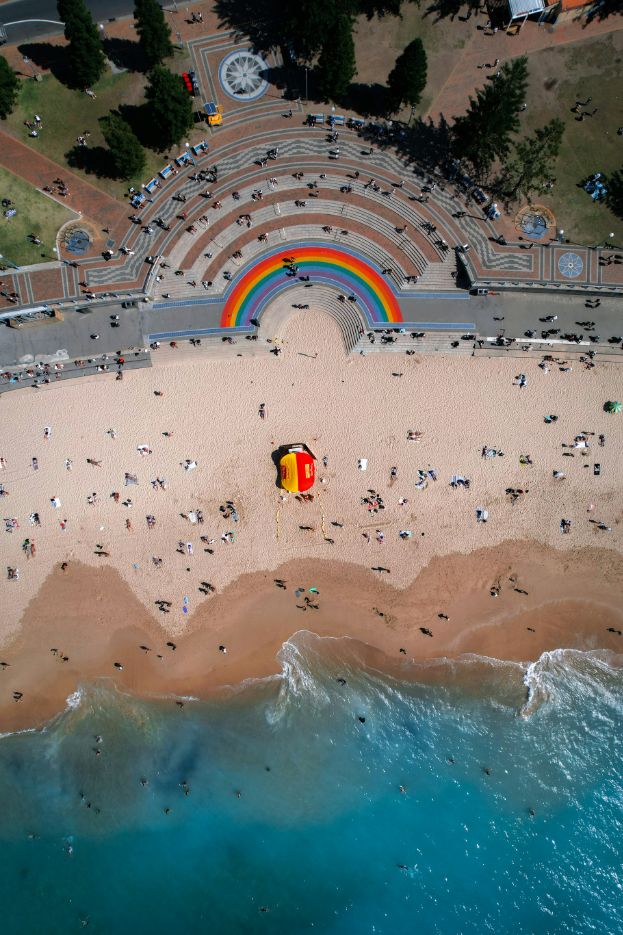
Coogee, NSW · First mortgage
$4m Business debt consolidation
Four commercial debts were consolidated into one facility. The borrower later refinanced to a bank.
Read case studyProperty-secured finance
Business finance from $50,000 across Australia, secured by eligible residential or commercial property.
See how business owners used property-secured finance to consolidate debt, fund working capital or keep an existing loan in place.
Coogee, NSW · First mortgage
Four commercial debts were consolidated into one facility. The borrower later refinanced to a bank.
Read case study
St Kilda, VIC · Second mortgage
Raised business funds while retaining an existing fixed-rate first mortgage.
Read case study
Mount Gambier, SA · Second mortgage
Used a commercial property to clear an ATO debt and release working capital.
Read case studyIndicative loan-to-value ratios for business-purpose first and second mortgages on eligible metropolitan property.
Second mortgage figures are combined LVR, including funded interest and fees. The lender assesses the address and valuation to determine the limit. Regional property is assessed individually.
Read the full LVR guideSee what to prepare, what we’ll discuss and how your loan can progress to settlement.
See what to send usTell us how much the business needs, what it’s for and the details of the property you’ll use as security.
If your scenario fits, we’ll explain the proposed loan, its costs and the information needed for assessment.
The lender reviews your application. Settlement follows formal approval and completion of the required checks and documents.
Step 1 of 2
We’ll use these details to respond to your enquiry. Privacy policy.
Guides for business owners and brokers and advisers.
A second mortgage may let you raise funds for your business while keeping the existing loan. We assess the total secured debt, the first lender’s requirements and how you plan to repay the additional loan.
Loans start at $50,000. The amount depends on the lender’s valuation, existing secured debt and the loan-to-value limit for the property’s location and type. We also assess how you’ll repay the loan.
We can generally provide indicative terms within 24–48 hours once we have enough information. Formal approval and settlement depend on the lender’s assessment, valuation and legal checks.
For an initial assessment, start with the property and loan details, including the estimated value, current debt and repayment plan. The lender may ask for financial statements and a formal valuation as the application progresses.
Innovate Funding funds selected first and second mortgages directly. For other deals, we may arrange finance through a private or non-bank lender. We explain the proposed arrangement before you decide whether to proceed.