

Private lending in Western Australia
Innovate Funding provides property-secured business finance in Western Australia from $50,000. We directly fund suitable first and second mortgages and may arrange other facilities through private and non-bank lending partners when a transaction falls outside our internal scope or funding capacity.
The property offered as security is central to the assessment. Whether your business operates in WA or elsewhere, we review the security address, accepted value, existing debt, business purpose and proposed repayment strategy.
For an overview of our national service, explore private lending across Australia.
WA security location and lending limits
Residential first mortgages are generally assessed up to 65% LVR for eligible metropolitan WA property. Selected residential second mortgages may also be considered up to 65% combined LVR, including the existing first mortgage and proposed second facility.
Commercial property lending is usually assessed around 50% LVR, with up to 60% considered, depending on property type, location and individual assessment. For a second mortgage, the commercial limit applies to combined secured exposure.
These figures allow for funded interest and fees. Lower limits may apply, and regional property requires individual review. The maximum dollar amount is assessed for the transaction. Read our LVR and borrowing limits guide for the calculation approach.
Where We Lend in Western Australia
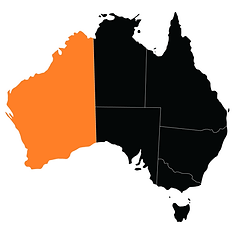
Innovate Funding provides private lending arrangements throughout Western Australia.
Metro WA
Perth: Fremantle, Joondalup, Midland, Rockingham, Armadale, Mandurah, Cannington, Baldivis, Morley

Regional WA
Bunbury, Albany, Busselton, Margaret River, Esperance, Katanning, Narrogin, Manjimup, Moora, Kalgoorlie, Coolgardie, Leonora, Geraldton, Carnarvon, Northampton, Karratha, Port Hedland, Newman, Broome, Derby, Kununurra.
Each property is assessed individually. Regional or rural security may attract lower lending limits. See our Australian lending coverage for other states and territories.
Choosing a property-secured structure
A first mortgage loan may suit an eligible business purchase or refinance where the new lender takes the first registered mortgage position. Existing debts being refinanced must be allowed for in the settlement figures.
A second mortgage may release equity behind an existing first mortgage, subject to its arrangements and lender approval. Retaining the first facility does not remove its repayment obligations.
Business bridging finance may address a funding gap pending a supported sale, refinance or business receipt. Typical terms are 3–12 months, with longer terms considered individually.
Funds may support working capital, equipment, verified business tax debt or refinancing business liabilities. The actual use of funds must qualify as a business purpose. Construction finance is generally arranged through specialist lending partners.
Establish the net funds you need
Tell us the amount your business needs after settlement deductions. The gross facility may also need to cover existing-debt payouts, funded interest and fees. Those amounts can reduce the cash available for the business.
Interest, establishment fees, brokerage, valuation and legal costs depend on the transaction. Compare the net advance, total repayment amount and any minimum-interest or early-repayment provisions before accepting terms.
Frequently asked questions
Can I apply if I live outside Western Australia?
Yes. You can submit a business-purpose funding scenario involving Western Australian property even if you live or operate elsewhere. Assessment considers the security property’s location, ownership, accepted value, existing debt and proposed repayment strategy. Borrower location does not guarantee property eligibility.
What LVR is available for a WA second mortgage?
Selected metropolitan residential second mortgage transactions in Western Australia may be considered up to 65% combined LVR. Commercial lending is usually assessed around 50% combined LVR, with up to 60% considered. These limits include existing and proposed secured exposure, including funded interest and fees. Lower limits may apply.
Do you consider properties outside Perth?
Potentially. Properties in Mandurah, Bunbury, the South West and other regional Western Australian locations are assessed individually. Property type, accepted valuation, marketability and the proposed exit affect whether funding is available and the lending limit that may apply.
Do I need full financial statements for an initial assessment?
Full financial statements are not required for an initial deal assessment. We still need details of the business purpose, property security, existing liabilities, funding requirement and repayment strategy. Requirements for formal approval depend on the lender and transaction.
How quickly can a private business loan settle in WA?
Innovate Funding can generally provide indicative terms within 24–48 hours after receiving sufficient information. Formal approval and settlement take additional time for assessment, any required valuation, legal documentation and funding conditions. Tell us your deadline when submitting the scenario.
Submit a WA funding scenario
Send your funding enquiry with the property address, estimated value, existing secured debt, net amount required, business purpose, preferred term and proposed exit. Include your settlement deadline and any arrears or approaching maturity date. Call 02 8919 3639 or email deals@innovatefunding.com.au.